
BUSINESS NEWS - When we think about heritage, we often think of things we can see, touch or pass down through generations - family recipes, cherished heirlooms, cultural traditions or perhaps property.
But there is another form of heritage that can have a lasting impact: our relationship with money.
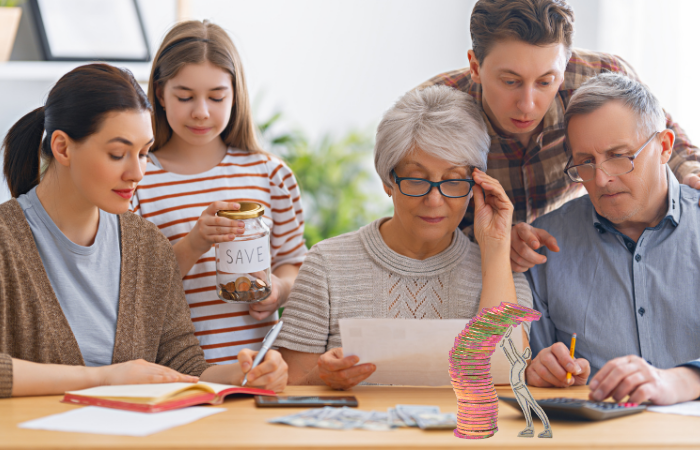
Long before children understand interest rates, investments or household budgets, they learn how money feels.
They notice whether finances are discussed openly or avoided, whether unexpected expenses are met with calm problem-solving or panic, and whether spending is planned or impulsive.
This creates what can be described as financial heritage - the attitudes, habits and beliefs about money that are passed from one generation to the next.
It is shaped every day by how parents and caregivers manage financial pressure, discuss priorities and involve children in age-appropriate money conversations.
Here are seven ways households can start building a healthier financial heritage.
1. Make money conversations normal
In many households, money remains a difficult or even taboo subject.
Breaking that cycle can start with making money a normal part of everyday conversations. Discussing the cost of groceries, saving for a family holiday or setting monthly priorities can help children understand that money is a practical tool to be managed rather than something that should automatically create anxiety.
These conversations can also help children develop a better understanding of the decisions that happen behind the scenes in a household.
2. Pass on the financial habits worth keeping
South Africa has a strong culture of financial resilience, with many households using strategies such as consistent saving, careful planning and community-based structures such as stokvels.
These habits can provide valuable lessons about discipline, preparation and working towards shared goals.
The key is to identify which financial traditions are helping the family build greater stability and intentionally pass those lessons on to the next generation.
3. Break financial patterns that no longer work
Not every financial habit inherited from previous generations needs to be carried forward.
Avoiding conversations about money, relying on unmanaged credit or spending to maintain appearances can become established patterns simply because they are familiar.
Recognising these behaviours is not about blaming previous generations. Instead, it creates an opportunity to decide which habits still serve the family and which should be changed.
4. Question the beliefs behind financial decisions
Financial decisions are often influenced by deeply held beliefs.
Ideas such as “money is always scarce”, “investing is only for wealthy people” or “talking about finances is inappropriate” can influence how people save, spend and plan for the future.
Identifying where these beliefs come from can help families replace anxiety-driven financial habits with more informed and constructive choices.
5. Remember that children learn by watching
Children often absorb financial lessons through observation rather than formal instruction.
Something as simple as comparing prices while shopping, explaining why a purchase is being postponed or showing teenagers how a household budget works can turn everyday activities into valuable financial lessons.
The important point is that children are learning from what happens around them, even when adults are not deliberately trying to teach them.
6. Create a healthier money culture at home
Financial wellbeing can become a shared family project.
Setting collective goals – whether saving for a home improvement, planning a holiday or working towards another family priority – can create accountability and help children understand the connection between everyday choices and longer-term goals.
Regularly discussing household finances in an age-appropriate way can also help family members understand the reasons behind financial decisions.
7. Turn good intentions into a financial plan
Creating a lasting financial heritage requires more than good intentions. It requires a structured approach that connects today's financial decisions with tomorrow's goals.
A comprehensive financial plan can help families consider their needs across different life stages, including saving, investing, protection and wealth transfer.
Working with a financial adviser can provide a framework that evolves as circumstances change, while helping families align their financial decisions with the values and goals they want to pass on.
Building a legacy starts with everyday choices
A healthy financial heritage is not about creating a mathematically perfect household overnight.
It is about building a more intentional financial foundation than the one you may have inherited.
The conversations you have, the habits you demonstrate and the choices you make today can all contribute to the financial lessons the next generation carries forward.
Ultimately, creating a healthier financial heritage is about giving the next generation a stronger platform from which to build.
‘We bring you the latest Garden Route, Hessequa, Karoo news’